Tuesday, February 12, 2013

Finding My Voice


Wanting to implement so many new changes into my life--- more careful spending, paring down possessions, healthy changes, budgeting, environmental consciousness, and time management--- can be tricky. I try to be aware that overloading my plate with goals can divide my energy and focus, which can inhibit my efforts. On a blog initially designed to be about finding wealth outside of income, I see my interests and passions have branched into other aspects of my life. Interestingly enough, I've learned to observe these goals as a collective rather than separately. All of these elements fall together under one common objective:

Mindfulness.

As someone who has tried to meditate, let me tell you... it's hard. I will devote twenty minutes to sitting in stillness and calm, trying to quiet my mind. Instead, I spend the entire time reminding myself to unclench my jaw, to breathe deeply, to stop thinking about various topics. I learned a meditation "trick" in college: when a thought enters your mind, visualize it as a piece of paper, then visualize crumpling up that paper and throwing it into a wastebasket. However, it seems that in my years since college I have spent more time sending mental paper balls flying all over the place and less time being in an actual meditative state. Turning my mind off and getting my body to respond to that is very difficult.

All of these goals I seek for myself are essentially asking me to be more mindful of my actions and decisions. I have been asking myself to be more present in these situations as they are happening, so they will in essence become fluid and natural reactions that don't require my constant mental attention. Though my aspirations may seem numerous, I find that I am seeing results because I have undergone a process of becoming more mindful without even realizing that's what I was doing.

For example, in the area of spending and budgeting, I have held fast to my new 2013 plan. Though I could see daily results while tallying my "play money" on my marker board, I didn't see my overall spending results until I received my recent credit card statement. When I compared it to the statement prior, I realized with my new budget that I had spent $521.54 less over a 30-day period. I'm not even on a spending fast anymore! During my time of financial fasting, I saved an average of $680 per month. I was beyond stunned that my results were so successful despite removing such an extreme limitation.

But then again, I shouldn't be stunned. My spending fasts have brought more awareness to my spending habits: how often I spend, on what, and why. I developed a mindfulness that has carried over into my budget plan. Despite my not being on a spending fast, I had actively changed my approach to money in a way that stuck.

Secondly, I've found that--- while I am more mindful of my spending--- I have also increased my awareness for what money actually means to me. When finances are strapped, it becomes a huge mental burden... one that caused a lot of stress following my divorce and my knee injury. Having the financial means to cover those expenses (plus my cost of living) means I spend less time thinking about money. I realize that, for me, having sufficient financial means does not tempt or encourage me to have excessive financial means.

I'm currently reading the book "Womenomics: Work Less, Achieve More, Live Better," and one of the major topics addressed in this text is that time is the new currency. The appeal of a more prestigious job and higher salary loses its value at the expense of exhausting demands and work hours. In this day and age, many people are seeking freedom and flexibility over larger paychecks. I can very much relate to this way of thinking. While I strive to do good work and to be an effective employee, I also know that I can't perform at my best if I don't have time to see loved ones, get enough sleep, or indulge in fun activities. That balance is more valuable to me than money.

I'd rather have
a balanced life of doing work I enjoy with time for healthy relationships and hobbies
instead of
a life of making a lot more money but not having the resource of time to make it worthwhile.

Lastly, I have detected a greater mindfulness in my personal health and well-being. Being more aware of what I eat (and the triggers that cause me to overeat or make poor meal choices) has resulted in a six-pound weight loss since January 1st. Now, I let my hunger trigger my decision to eat instead of the sight of food triggering a feeling of hunger. I know I have a sweet tooth, and I allow for that indulgence without going overboard. I've also become more aware of physical misalignment: when I experience pain in my lower back or shoulders, when I begin to have frequent headaches, when I feel drained. I've incorporated yoga into my exercise regimen to help lower my heart rate at the end of the day, and to stretch out some of those tightened problem areas. I find that I am largely tense in my neck, lower back, hips, and feet.

Because I am becoming more mindful of my health, my spending, and my values, it helps me to better establish my blog voice. I feel I have a better understanding of how to incorporate and intersect these various aspects of my journey into one common goal, thus making my future posts more cohesive. I've been able to see my changing body and my changing bank account... but perhaps my changing mindset is the most dynamic of all.


...Ugh, that was a cliché way to end a post. My apologies.


Tuesday, February 5, 2013

January Results


This post has been delayed due to personal matters, so please excuse the brevity.

I came in under budget for the month of January, despite having to spend $50 over my gas budget for additional commuting. I rather like the transparency of writing each purchase on a dry erase board in my kitchen. For me, it was better for accountability than writing it in a checkbook and then tucking it out of sight. Because of steps I've taken earlier in my journey with spending fasts (then out of necessity) it has been a smoother transition to drastically reduce spending (now willingly and voluntarily). That money has gone straight into my savings account, along with the (small) profits of selling a few more unwanted items on eBay. Something is better than nothing.

I also adhered to my modified eating and exercise habits. I've lost six pounds since January 1st, and most of it can be attributed to dietary changes. For one week at the end of the month, I was ravenous. My stomach grumbled and ached with hunger all the time. Without agonizing over numbers and calories too much, I'd eat something small or drink a little juice to stave off the pangs. My body was clearly used to consuming more (much like my wallet had) and while I was not starving, my body was certainly reacting to the adjustment.  Regarding exercise, sometimes my workout only consisted of twenty minutes of light activity. However something is better than nothing.

Again, apologies for the limited content of this post. Something is better than nothing, right?

Tuesday, January 22, 2013

The Bittersweet Epiphany


In 2008, when I was twenty-four years old, I wrote on my Facebook page that while I enjoy the conveniences and technology of modern times, I could easily sell off most of my possessions and move somewhere remote. Yet, one year later, my blog was filled with desires to have a large, lush wardrobe and a massive record collection. I wanted a different job that paid more money so I could make numerous cosmetic upgrades to my home and to eat at fancy restaurants.

When I got divorced in 2011, my expenses doubled. I was now paying the full mortgage and utilities instead of just half. I also took a 10% pay cut at work due to budget constraints. Now, I had to pay more bills with less money. Shortly after, a distracted driver hit me on the freeway and totaled my car. Then, my dishwasher malfunctioned and flooded my kitchen. Finally, there was that knee injury and its related expenses. And I couldn't help but whine to myself about it... at first.

The end of my marriage forced some obvious change, but it also instigated some more gradual shifts in my approach to life. I didn't like my ex-husband's attachment to money and things, and I was beginning to notice a correlation with my own version of materialism. Sometimes an event can change the course of how we see things, and the exposure is bittersweet. It's so challenging to think you know what you want and how to live well, and to have that notion blown to smithereens. It created an uneasiness in me, and I could feel my heart grasping out into the void for attachment and meaning. The process of enduring that was very uncomfortable, but crucial to the growth that followed.

Despite the daunting task of restructuring my life views, I no longer had the deceptive veil over my eyes. Inevitably, I had to shift to a different way of spending, or I wouldn't be able to afford my home. I felt trapped by my house, which I'd owned for less than a year; I couldn't sell it because I had no equity, and I couldn't afford to keep living the way I was. I wanted to seek release by going out with friends or indulging in retail therapy, but would stay home alone knowing I couldn't afford it. I found that I couldn't pay my mortgage in full by myself; I had to ask my family for help. I am so fortunate to have such helpful, loving parents who were capable of financially assisting me... But I felt I was letting myself down because I'd lost my independence. All of this was better than staying in a toxic marriage, right? Right? At the time, I was very unsure.

While I had always been fiscally responsible with a budget, I now had to get more selective and more creative with my finances. As my knee surgery loomed, I knew I'd need to account for copays and expenses not covered by my insurance. I challenged myself to a spending fast for one month, and though the process was very difficult at times, the final results astounded me. Resisting that initial urge to spend when everyone else wanted to see the latest film or go out for a drink paid off in the long run, and I was able to cover my additional expenses without dipping into my savings.

The results didn't last, however, because I went back to my old method of budgeting. I realized I couldn't go on a spending "diet," because like food diets, they are temporary and yield temporary results. My mind shifted again to that twenty-four-year-old me, who didn't yet see the wisdom in her own words. I began to read blogs and books about minimalism, and the idea resonated with me immediately. Shortly thereafter, I was selling my possessions online or donating them. I was being more mindful of what I did choose to acquire.

I fasted on my spending again, this time for two months. During this period of fasting, I became even more aware of what I truly value. I know that I want to get rid of more stuff, and invest more of my time in experiences: enjoying the company of loved ones, playing guitar, being outdoors, reading a book, painting, exploring. I want to spend less time living vicariously through the Internet and more time seeing things with my own eyes and hearing them with my ears and touching them with my hands. I also want to regain my financial independence and invest in my future. Most of all, I want to drink in new cultures and obtain fresh perspectives in a way that only travel can provide.

Wednesday, January 16, 2013

Money-Saving Tricks For You To Start Using RIGHT NOW!


These tactics work for me. I'm not a financial expert or debt counselor, so consider yourself disclaimer'd:
  • I don't care if the drive-thru "value menu" seems cost-effective. Rarely is the phrase "cheap and easy" ever a compliment. It costs far less to buy your own ingredients, put in some time and elbow grease, and make meals yourself (see photo above, and click to see a larger version). If your concern is that you don't have enough time to do this, consider making several meals' worth of food one evening or weekend when you do have time. Then portion off leftovers and store accordingly. If you're complaining about the time factor, then eating healthier food while saving money is honestly not really a priority for you. You will make the time for what you value most. So quit complaining, then, and enjoy your Taco Bell.
  • Don't bring cash with you anywhere. Keep one credit card on hand for emergencies, and make sure it has a low balance. This inhibits impulse spending. If you don't have the money with you, you can't spend it.
  • Pack meals and snacks ahead of time. It took me a while to adjust to this, but now I completely avoid the office kitchen and lobby cafĂ© because I can fulfill my hunger urges with better options. I find that I don't pine for the doughnuts and cookies if I'm armed with something satisfying, like a homemade trail mix or granola, fruit, carrots with hummus, or tea. I actually have a box of tea on my desk, so I can make something flavorful to curb hunger (often times what feels like hunger is dehydration anyway). I even keep some instant hot cocoa packets around for those inevitable sweet tooth cravings.
  • Keep a water bottle with you. No sense in paying for bottled stuff that isn't any different from what's in the drinking fountain. I even have a water bottle with a built-in carbon filter, so I can fill up with tap water when I'm on the go and it doesn't taste like butt.
  • Libraries! You have free access to books, music, videos, learn a new language, even surf the internet if you don't want to pay for that anymore. Of course, late fees are not free, so be timely in your returns as well. Wen the weather is pleasant, I've been known to walk a mile to the library, pick out a book or movie, and walk home. I just exercised and picked up some evening entertainment, without spending a penny.
  • Having a social life can add up: a cocktail here, a lunch outing there. For date nights it is easy to go out for dinner or see a movie. Consider paring down the spending without losing out on time with your favorite people: invite friends over for movie night (free from the library, perhaps!), to play board games, to do a clothing swap (hello, free new wardrobe!), to have a drink (buying the wine or beer--- or mixing drinks yourself---- is way cheaper), or just to sit around and chat. Sit in front of the fireplace, if you have one. If not, sit in front of a TV or computer screen playing video of a crackling fire. Go outside, play yard games. If the weather sucks, stay inside and roast marshmallows over unscented candles (yes, this works when you really want a s'mores in January)! Take turns cooking for each other, making cocktails for each other, hosting BYOB or potluck gatherings. One group of my friends likes to host theme parties and set up their own photo booth with a camera and props. This is much more fun, much more creative, and much more wallet-friendly. If you must go out, only have one alcoholic drink, or seek out local specials, or watch a movie in the cheap seats.
  • Turn off Groupon and other coupon e-mails. Seeing stuff offered for a fraction of what they normally cost will--- surprise!--- really influence you to make a purchase. I actually set up filters in my Gmail account to automatically send any of these coupon offers to a folder without even appearing in my inbox. You could also just unsubscribe from everything, too.
  • Stay out of the mall, dammit! There is nothing in there you need. You need groceries, you may need gas for your car, you may need electricity... none of these things are at the mall. If your weakness is Target or TJ Maxx, don't go there either. Just don't. If you think you have an exception to that rule, you're wrong. If you really wanted to, you could live your life without ever setting foot in Target or Wal-Mart again. I once stayed away for five months and didn't miss it. Their stuff may seem cheaper, but it also breaks or wears out faster when it's cheap, so you have to go back and buy more. If you must buy, take the extra time to seek out an item from a locally-owned business. You will also go in one day intending to buy cat food, and you'll walk out with a new scarf and lipstick and DVD and pants and... now you've hit a setback. Know your weaknesses and avoid them.
  • Those things your grandparents used to do? Learn them. If you tear a seam in the sleeve of your shirt, could you sew it instead of throwing it out and buying a new one? I bet you could learn. Instead of paying several dollars for a loaf of bread, could you make it by hand for mere pennies? I bet you could learn. If your car gets a flat tire, could you change it yourself instead of calling AAA? I bet you could learn. Could you create your own laundry detergent for a few coins instead of dropping eight bucks on a jug at the store? I bet you could learn. Acquire a skill that modern conveniences have all but dismissed a need for, and you'll not only be cool like MacGuyver, but you'll be saving dollars, too.
  • Get rid of your $#!T. By setting up an eBay account, you can take pictures of stuff you no longer want and sell it to someone who does. I made over $500 from September to December just by selling things I wasn't even using! (And then I used that moeny to pay my mortgage... how sexy!) I'll cover the world of eBay in another post. Craigslist is also an option, if you're trying to sell items like furniture or kitchen appliances. You could even take a carload of items to Goodwill and write it off on your taxes. If you itemize and list what you donate before you drop it off, you can see savings come tax season.
  • Don't use the car if you don't have to. This doesn't apply to everyone, but reducing your time in a vehicle can cut costs rapidly. You save on fuel, you save on wear and tear, and if you walk or bike to your destination you can give yourself some health points as well.
  • Post a picture or other reminder of what it is you REALLY want, and refer to it all the time. Each time you decide to buy a new nail polish, or order a new item of clothing, or grab a latte on-the-go, or impulsively buy a bunch of exotic cheeses, you are taking away money that will pay for your rent/mortgage/debt recovery/travel dreams/college loans/slimmer waistline/new camera or scooter or thing that would truly mean a lot to you. When you keep pining for something but don't have the funds, or if you're stressing about being able to pay the bills on a monthly basis, then you're depriving yourself of the peace of mind you genuinely want. You're sacrificing the big desire for a short-term one, and you're only hurting yourself.
  • MAKE A BUDGET AND STICK TO IT! Learn how to track your spending, sit down and do some math to figure out your average cost in categories like food and gas and rent, and don't spend more than you make. Then honor it. Have someone help you set one up the first time if you're feeling overwhelmed. Keep tabs on it, and don't deviate. You know how when you gorge your face on holiday food over two weeks in December and suddenly you're thinking, "Whoa, these must be someone else's pants!" because they don't fit? You have no one to blame but yourself and your impulsiveness. Fiscal responsibility will prevent your debt's waistline from expanding. If you don't want to honestly face where your money goes (mine was always getting sucked up in new clothes and dining out), then you can't complain when you've got a house full of collectible Voltron toys but no money to fix that alternator in your car. Seriously, you're a grown-up. Don't be an idiot. Make a budget, be straight with yourself, and adhere to it.

Do you have any money-saving tricks that work for you? Knowledge is the real wealth... share away! 


Monday, January 14, 2013

Goals For The New Year


My 2013 New Year's Resolution is to continue trimming away the excess in my life so that I can have the time and energy to appreciate what I truly value: my loved ones, my health/wellness, my faith, my work purpose, and my hobbies. To prioritize those things will mean limiting time on distractions, half-hearted commitments, wasteful spending, time in front of screens, and uninspiring people.

There are other lifestyle goals I want to strive for this year as well. I know it's better to focus on just a few things, but I really like to make lists! Some of these changes have already been implemented and are in progress:
  • Become a better photographer
  • Improve my posture, both seated and standing
  • Take the stairs at work
  • Bring my own snacks to work - no eating office treats!
  • Make and log daily food menus at least one day in advance
  • Eat green vegetables five days per week
  • Cook more meals in bulk and freeze extra servings for later
  • Eat at the table for dinner, with the television and phone turned off
  • Learn to cook fish well
  • Make pasta from scratch
  • Save bacon fat in a mason jar to use for more flavorful cooking
  • Consume no more than one serving of soda per month
  • Floss regularly
  • Read at least one book per month
  • Make my own mercury glass
  • Follow my budget plan to save for future home renovations, a new car, travel, and retirement
This, of course, is in addition to my 30 Before 30 list... which is less a list of goals and more of a challenge to try things that interest me. So far, I've knocked off #22 (master a specific cocktail... where I learned to make the Flaming Volcano) and #27 (receive a handwritten love letter... which of course came from the wonderful beau).

So far this month, I've taken the steps at work all but two days (on one day I was carrying a lot of equipment, and on another I wore wobbly shoes). I have logged my food daily, but have not been as diligent about making menus on the weekends. I haven't snacked on office treats, nor have I consumed any soda. I've stuck to my green vegetable rule, and am nearly finished with the book I'm currently reading. The budget is going well (I've spent about half of my allotment so I'm right on schedule). I haven't touched my dental floss arsenal, and I'm horrid about eating in front of my computer. As I keep making adjustments, hopefully I'll improve in those areas.

Tuesday, January 8, 2013

My Super Simple 2013 Budget Plan


To make sure my spending stays in check this year, I decided to make it much easier on myself when it came to writing up my 2013 budget. The less number-crunching and maneuvering I have to do, the better. After all, I'm trying to simplify my life. Who doesn't like simple, effective budgeting?

(I do feel compelled to emphasize that I am not a professional numbers gal, so while you may feel free to use this method for inspiration, I by no means guarantee its effectiveness!)

Okay, fine print out of the way. Here we go!

Fixed Expenses
These are the bills I will have to pay monthly or seasonally, and it also includes guaranteed expesnes. Some of them won't change at all from month to month, and others can be variable. I calculated the average amount I spend on those categories each month (of if it's something like a seasonal bill or an insurance premium, I calculated what the monthly expense would be). These fixed expenses include:
  • Mortgage
  • Internet
  • Cell Phone
  • Charitable Donation
  • Gym Membership
  • Netflix Account
  • Monthly Savings Deposit (10% of my net income)
  • Credit Card (zero-interest fixed payments on a piece of furniture I bought)
  • Water/Sewer (quarterly bill, calculated by dividing average bill by three)
  • Energy (variable, calculated using average yearly expense, divided by twelve)
  • Car Insurance (bi-annual expense, calculated by dividing by six)
  • Home Insurance (annual expense, calculated by dividing my twelve) - Added March 2013
  • Groceries (guaranteed expense, calculated by average monthly spending over past year)
  • Car Fuel (guaranteed expense, calculated by average monthly spending over past year)

Everything Else
I call this money "play money." That doesn't refer to the fake currency used in games like Monopoly or Life, but rather the entire remaining amount of my monthly net income after all guaranteed expenses are paid. These expenses include (but are not limited to):
  • Dining Out
  • Cocktails
  • Clothing
  • Gifts
  • Entertainment (movies, concerts, sporting events, etc.)
  • Toiletries (make-up, shampoo, tissue, soap, etc.)
  • Household Needs (repairs, cleaning supplies, tools, etc.)
  • Medical (prescriptions, co-pays, supplies, etc.)
  • Miscellaneous (books, games, shoes, decor, electronics, shipping costs, travel, etc.)
  • Emergencies (flat tire, tow truck, hospital visit, repairman, etc.)

Once all of the fixed items were calculated, I subtracted them from my monthly net income. I only counted my guaranteed full-time paycheck, because eBay sales and freelance gigs are too inconsistent for me to rely on. (But hey, that means when I do receive alternative income, it's a happy bonus!) The remaining amount is my Play Money. This is the amount of money I really have to spend for the entire month. When it's gone, it's gone.

Monthly Net Income - Monthly Fixed Expenses = Monthly Play Money

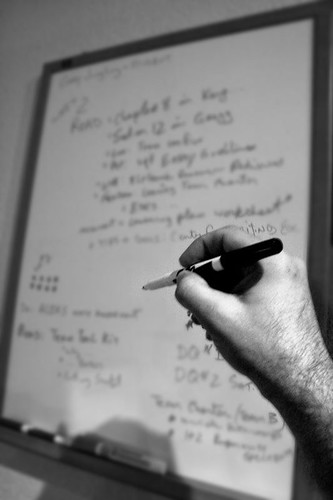
I wrote this number at the top of a magnetic marker board I keep on my fridge. As I spend money--- on anything from shoes to chai lattes to body lotion to furnace repairs--- I write the amount of the expense below my Play Money total, and then calculate the remaining amount. Over time, the Play Money budget begins to look like a long subtraction problem from elementary school arithmetic:
Example
  430.00
-   28.48__
  401.52
-   71.67__
  329.85
-     4.31__
  325.54
   (etc.)
Once this number gets to zero, I can't spend any more money for the month... logically, because I don't have any money to spend. I need to make sure I cover my guaranteed expenses. I like to leave the whole subtraction problem up throughout the month (though you could always just re-write the new amount if you want to save space). I prefer to see exactly where it is going and how quickly it leaves my pocket, so I can catch wayward spending before it gets too out of hand. This method should keep me from overspending because I can scale back any purchases if the Play Money account gets too low early on.

That's it. Some initial number-crunching leads to only dealing with one simple math problem for the rest of the year. Even better: whatever I don't spend can go into my savings!

Friday, January 4, 2013

Spending Fast: The Results


A nearly two-month attempt at a spending fast concluded with the arrival of the New Year. So, how did I do?

I'll cut straight to the meaty parts. In comparison to my spending in October, I saved an average of $680 each month in November and December. December fared slightly better, despite holiday shopping. Most of my gift spending was on food ingredients to make my gifts for others.

My biggest deductions were in medical bills (because it's been nearly a year since my injury and the expenses for that are winding down), clothing (because I stopped buying it!), and dining out (though the beau did kindly cover the cost of some restaurant outings). Grocery expenses went down, but not by much (likely due to the consumable gifts I made for Christmas). Car fuel and entertainment spending barely changed. All other expenses are fixed and minimally variable.

For several months (during my attempt at a mere spending "diet"), I was actually having to take money out of my savings in order to pay my monthly expenses. There were several reasons for this: pay cut due to smaller budgets at work, application fees for a house re-finance, initial expenses for a freelance project (later reimbursed but not for several months), a car insurance premium payment, and higher medical bills due to copays from my physical therapy. But also, I was not really monitoring what I really spent money on. A coffee shop visit here, a DVD there... It didn't seem worth tracking in my mind since the expenses were minor on their own; however, they added up. Eventually I was looking at my monthly credit card statement and it was higher than the amount in my checking account.

(For the record, I make virtually every purchase on a credit card and pay it off in full at the end of the month, in order to earn rewards points. This method can get out of hand very quickly for impulse spenders, so I don't recommend it unless you really will pay off your bill each month without exception.)

To prevent making interest payments, I'd reluctantly remove some money from my nest-egg and take the hit, with plans to replenish it as soon as I got my next paycheck. But slowly, over many months, I found I'd removed over $2000 from my emergency fund. Yikes.

With the savings from my two-month Spending Fast, I was able to replenish over half of what I'd removed (twice as quickly as it took for me to spend it initially, at that!) and to finally breathe a sigh of relief. Feeling fiscally secure is much more rewarding than anything I bought during that strained season in 2012.

Now it's a new year, and it's time for a new budget. I'm going about my spending habits in a whole new way, to ensure I won't be pulling any surprise funding from my savings ever again. I'll cover my budget plan in my next post.

Saturday, December 29, 2012

The Great Knick-Knack Purge And Why I Chose To Become A Minimalist


Over 60 books once gathering dust in my home have now found new purpose at my local public library. The man who accepted my box of books seemed super excited to have them. I also donated another full carload to Goodwill this month. I carefully itemized everything before I brought it over, and will submit that information come tax season. Who knows... if our country falls off this fiscal cliff, these donations might really help my with the extra costs I would accrue!

There is a pile of items in my basement that I plan to sell, and each item was noted in detail and photographed before being put into storage. Now I can post them online at my convenience and watch them slowly find new homes where they will be more appreciated.

I also have one (yes, only one) box filled with sentimental items from my childhood. This box is mostly photographs and papers (which I plan to digitize) and precious small toys or stuffed animals. The box is only half full.

My attic currently only stores my window air conditioner, my suitcase, a bin filled with Halloween costumes and decorations, and a bin of outdoor winter gear. I've reduced my Christmas decorations to one box, along with one box for ornaments, and one box that contains my fake tree.

I have also been filtering through the items in my old room at my parents' house. I used to hoard a lot of paper, because I'd see an article or an image that inspired me and I'd tear it out and save it (these were the days before Pinterest). I ended up recycling about 9/10 of that massive stack. What's left are some personal documents, a few images, and some posters that I can sell to forever fans (people still collect Linkin Park stuff, right?). I've already made some money on items I've sold, and it has happily padded my savings account while stripping away unwanted things.

There is an inevitable moment during the minimizing process where the question arises: "Why did I ever think I needed all of these things?" It's taken me years to acquire all this stuff, and I'm sure it will take me a while to whittle down my possessions... if anything, to adjust to the change it brings along the way and how it forces me to live a little deeper than what I own.

That brought me to ask myself a follow-up question: "What was the watershed moment, one that made me realize I wanted to change and live more simply?" Just three years ago I was writing in my blog about how I wanted a massive closet filled with clothing and how I wanted a gigantic record collection, etc. It was all about quantity, or so I thought. Then... I got married.

I wed someone who very much enjoyed having things. It was about acquiring more, because if he had things, that meant to others that he had the money to buy them. It was a representation of what he valued; appearance was the priority. I found myself becoming disgusted with the stuff he accumulated, without really understanding the correlation that I was collecting things I thought valued, too.

When the marriage ended, it left me with a lot to think about. I was about to start a new chapter in my life. How did I want it to look? He had taken his things with him, and I found that a more spacious home really appealed to me. I began reading inspirational blogs (listed on the right hand side of my page) and understanding that what I craved was a simpler, more minimal lifestyle. It became apparent to me that I still wanted nice clothes and great records, but it became more about the quality of what I acquired. Will I wear this dress? Do I even listen to this band? Should I buy it because it is cheap or on sale or given to me for free? Should I keep it even if I paid full price but I never use it? Assessing what I really wanted to keep made it easier for me to part with the rest. I still have a healthy wardrobe and a record collection, but I've pared it down to what I use frequently and love the most.

One would think this is a common sense approach. Honestly, I thought what I was buying had use and value to me at the time. Before I knew it, I felt more tied down by my stuff than excited by it. The consumer bug had his claws in me, big time, and I hadn't even seen how it was changing me. I was also seeking happiness in things to distract myself from the unhappiness in my marriage.

The divorce had me looking at other areas of my life that I wanted to improve. I discovered I was utterly disgusted with materialism and ended up going very much in the opposite direction in a very short time. Though I dove into minimalism rather assertively, I have found I truly enjoy it. There has not been one regret as I donate, sell, or give away something I once deemed worthy enough to take up space in my home. My life has become more about quality, in many ways.

Monday, December 10, 2012

Attitude Adjustment


I hadn't written a blog entry in a while, mostly because I hadn't felt like writing. Stress and frustration had whittled down my energy and left me with a sour attitude. Everyday factors tend to add up and start to feel overwhelming, especially around the holidays. There is plenty to be thankful for, and I am indeed blessed, but every now and then the burdens start to weigh me down.

All of that yuck came to a pleasant halt recently. I was having a particularly bad day at work. This time of year is busy because I'm filming a lot of holiday programs in various schools. It's easy to fall behind when other tasks are assigned and when technology glitches hold up the assembly line. I narrowly made a deadline by late morning, then rushed to a school to do some filming... only to realize I had forgotten to bring tapes for the camera. I'd already missed one appointment to film at this school, and now I was going to have to postpone it again. I was so frustrated and felt terrible.

The librarian, who had asked me to shoot this video for her, was incredibly understanding. I'd never met her before, as she had just been hired one month ago. She wanted me to tape a group of her best-behaved kindergarten students checking out books in an orderly manner, to use as an example to show other classes. Not only was she gracious enough to reschedule with me yet again, she offered to let me stay and watch the kids so they could "practice" acting in front of the camera.

The next half hour was such a pleasant experience. She sat the students down in a group on the floor, and told them, "Boys and girls, I have a surprise for you.... Did you know that we are a FISH school? Do you know what that means?" And she used this method to proceed to tell the kids about the FISH philosophy and the rules to abide by FISH. She had printed the rules onto giant paper word balloons, laminated them, and placed them on various posters in the library. Aaron Rodgers, a crocodile, puppies, and One Direction were all "speaking" these guidelines for FISH.

Then she read "The Gingerbread Man" to the students. Part of the way through, when the Gingerbread Man runs away from a sow, she set down the story and asked if anyone understood what a sow was. Her voice never came above a soft-spoken tone, never lost patience, and the kids obediently listened and read along with her. They stayed put in their seats and always raised their hand to answer her inquiries. I was astonished by the effectiveness of her communication.

When it came time to check out their own books, she would look at one individual kindergartener and say, "You, my love, may go." She did this one at a time for each student, to keep the flow of traffic down.  Eventually she changed her compliments and began addressing kids by different names: "You may go, Cutie Patootie. Mr. Muscles, you may go." Some kids didn't return their old books so they couldn't check out new ones. She kindly asked, "Remind me dears... what happens when you don't need to check out a book today?" One child excitedly responded, "We get to go read a magazine!" The librarian smiled and said, "Oh! I knew you'd remember!"

Afterwards, I pulled the librarian aside and thanked her for the opportunity to shadow her class. I told her that I spend my days in a stuffy office building with a bunch of grumpy adults. This was the refreshment I needed to change my attitude. She beamed at me and referred to a poster in her library that said "Attitude is Everything. How will you choose to see today?"

I realized at that moment that part of my stress was in how I viewed the situation. I decided that in spite of a tough economy, a job where I am overworked and undervalued, my stubborn weight not budging despite my efforts to change it, my worries about gifts this year for loved ones, family obligations, and the feeling of drowning in my own stuff... I was going to look at it differently.

First, I needed to be honest with myself. I've been logging all of my food intake and fitness minutes on SparkPeople. Since I started tracking on September 1st, one third of the days have been over the limit for calorie intake. How can I expect to see results when I'm overeating 33% of the time? Many times it wasn't by much, but having two or three cheat days a week is not a lifestyle change. I needed to admit I was being too lax with my self-accountability. (Since remedying this, I have only gone over on one day, and the scale has started to tip back in my favor. Who knew?)

Secondly, I was able to convince my beau to get a gym membership. He had been interested in it for some time, but he needed to be ready to commit. Now we're workout buddies and we go at least twice a week. On other days I work out from home, or we play dance games on the Wii. Not enough time has passed to see real results yet, but I am increasing my lifts on the weight machines. I can feel by body strengthening and toning. I also started taking a kickboxing class at the gym every Thursday. Because of my Insanity workouts, I can run with high knees longer than anyone else in the group! I know what it feel like to push myself past the level of discomfort and know that it won't kill me. If I am not a sweaty panting heap by the end of a workout, I now feel like I've cheated myself. I sleep so much better after I exercise, too!

Next, I sent an open letter to my relatives, encouraging them to think about our Christmas traditions and if we might consider changing them up a bit. I wanted to know if anyone else would be open to foregoing the gift exchange this year to eliminate a little time and financial burden. I didn't get any response, but I feel good about throwing my idea out there. Maybe they'll think about it. We're all working-age adults now, and most open gifts with their immediate families anyway.

Finally, I committed a weekend to putting a bunch of my stuff on eBay. I was quite surprised to discover there has been a bidding war on my 3-foot-tall plush Bugs Bunny toy from childhood; it's up to $60. And here I was just going to donate it to Goodwill! It feels great to get rid of things I don't want and lighten the load on myself. It's also great to ensure these items go to someone who wants them instead of just winding up in the trash.

As far as work goes... there isn't a whole lot I can do, but I'm working with what I can. I'm in the process of moving out of my shared office and into my own space. It's just a corner of a large room that is mostly used for storage, but now I won't be interrupted when I'm editing. It gives me a quiet space to concentrate and do better work. I've been trying to get a meeting with my boss since July, but I can't even get his secretary to e-mail me back. I'm not sure why it is so difficult to make an appointment, but I will keep trying.

And of course, there's the perk of making friends with that new librarian. She and I plan to have lunches together from week to week. Most of my office building consists of people at least twice my age, with adult kids of their own, so it's really refreshing to have a co-worker near my age to hang out with! She's just such an encouraging influence, and a reminder that I have more control over the state of things that I may realize.

There are some circumstances I can't change, but I can change how I approach them. Also, check out this well-written guide to getting what you want. And good luck to you on pursuing what you want! It may only be as far away as an attitude adjustment.

"You, my love, may go..."


Tuesday, November 20, 2012

Cutting The Majority


Since turning my Spending Diet into a Spending Fast, I've made quite a bit of progress. I did learn that I pay more per month in medical bills than I thought. A co-pay here and there really can add up, and I should have been paying attention more closely. That aside, I've also made some strides in changing the trajectory of my finances. I have avoided excessive spending in the following ways:
  • I gave my nephew a birthday gift that I already owned. He wanted the game of Twister, and I had actually purchased it for myself a few months ago. It was in my closet, still unopened. I made his birthday card using existing scrapbook supplies. That was easy!
  • I purchased groceries using coupons and a $20 voucher I purchased last month for half price. I'm still using up produce from my CSA, and my freezer and pantry are very well-stocked, so I only bought a few things: tomatoes, peanut butter, almond milk, hummus.
  • I have dined with the beau several times this month, but he has always generously picked up the tab. He knows about my spending fast and doesn't pressure me to pay when we go out, but I am starting to feel bad and don't want to seem like a mooch. I paid for my share of dinner one night. I also bought lunch while out with a friend I hadn't seen in a while. Otherwise, I have not purchased any other beverages or meals at restaurants or coffee shops.
  • I have not purchased any clothing, accessories, or luxury items. I did pay $25 for a haircut... my first in four months.
  • I have minimized my driving by not going out to restaurants or bars or entertainment venues, so I've only had to fill my tank once this month.
I calculated my average monthly spending in these categories: mortgage, energy, water/sewer, internet, cell phone, car insurance, gym membership, credit card payment, groceries, gas, entertainment, clothing, house repairs, medical bills, tithe, and miscellaneous. I did this by adding up the total spending for each of the past four months, then combining the total and then dividing by four.

I have been on budget for this month's fixed expenses (mortgage, energy, water/sewer, internet, cell phone, car insurance, gym membership, credit card, tithe). I have spent $126.56 less on groceries. I have spent $100.17 less on gasoline. I've only shelled $16 all month on dining expenses. For entertainment, I've maintained my Netflix account but nixed any other spending in that category. I have spent zero on house items, clothing, and accessories (and donated over $700 worth of items to Goodwill!). My medical bills have decreased by half. My miscellaneous spending (a gift for a baby shower and a haircut) totaled $57.

When comparing my November spending to the average of the previous four months, I have cut my expenses by 51%. Yep, you read that right... I spent less than half of what I normally do... cutting the majority of my expenses. And I didn't even have to cut out my Netflix or internet or gym membership. It was that simple. It seems so wasteful, in hindsight. I didn't need to spend money on any of those things I used to, all while believing I was being fiscally responsible. Just goes to show the belt can almost always get a little tighter.

My spending fast has been so successful that I plan to continue it into December. It will be a welcome challenge to navigate the national holiday spending frenzy in a minimalist way.